
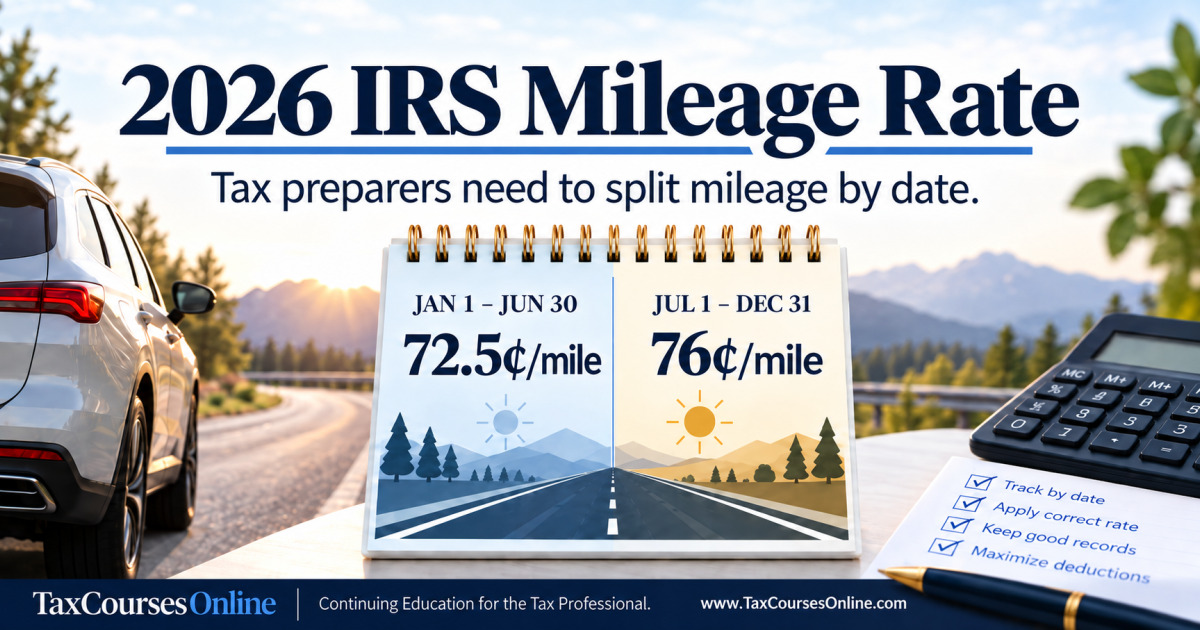
For business use, the 2026 standard mileage rate is:
| Period | Business mileage rate |
|---|---|
| January 1–June 30, 2026 | 72.5¢ per mile |
| July 1–December 31, 2026 | 76¢ per mile |
The IRS raised the rate beginning July 1, 2026, after revising the standard mileage rates because of higher fuel costs.
2026 mileage cannot be calculated using a single annual rate.
What Tax Preparers Need to Do Differently in 2026
For clients using the standard mileage method, preparers should separate qualifying mileage into two periods:
- January 1 through June 30, 2026
- July 1 through December 31, 2026
Apply the correct rate to each period, then combine the results.
Split-year calculation example
Assume a self-employed taxpayer drove 4,000 business miles from January through June and 3,000 business miles from July through December.
4,000 × $0.725 = $2,900
3,000 × $0.76 = $2,280
Total standard mileage amount: $5,180
Using one rate for all 7,000 miles would produce the wrong result.
2026 IRS Mileage Rates
| Mileage type | Jan. 1–June 30 | July 1–Dec. 31 |
|---|---|---|
| Business | 72.5¢ | 76¢ |
| Medical | 20.5¢ | 23.5¢ |
| Moving* | 20.5¢ | 23.5¢ |
| Charitable | 14¢ | 14¢ |
*The moving rate applies only where the taxpayer qualifies under applicable federal rules.
The charitable mileage rate remains 14¢ per mile because it is fixed by statute.
Why Did the IRS Change the Mileage Rate Midyear?
The IRS originally set the 2026 business standard mileage rate at 72.5 cents per mile beginning January 1. It later raised the rate to 76 cents per mile beginning July 1 because of higher fuel costs.
The medical and qualifying moving rate also increased from 20.5 cents to 23.5 cents per mile beginning July 1.
A midyear mileage-rate change is unusual, which makes accurate date-based records especially important for 2026.
Does the New Rate Apply to Employee Mileage Reimbursements?
The revised rate applies to mileage allowances paid on or after July 1 when the underlying transportation expense was also incurred on or after July 1.
Mileage for travel before July 1 remains subject to the earlier 2026 rate. Employers and payroll or expense systems should distinguish first-half and second-half mileage rather than simply replacing one annual rate.
The IRS rate is commonly used for employee reimbursement, but employers are not necessarily required to reimburse at exactly that rate. The tax treatment depends on the reimbursement arrangement, including whether it satisfies accountable-plan requirements.
Mileage Records Matter More in a Split-Rate Year
Mileage records should generally identify:
- date of trip
- mileage driven
- business destination
- business purpose
- total business mileage
- total annual mileage
Contemporaneous records such as a mileage log, app, spreadsheet or diary can help substantiate the deduction. In 2026, the date of each trip is especially important because it determines which mileage rate applies.
Standard Mileage Rate vs. Actual Vehicle Expenses
The standard mileage rate is an optional method for calculating deductible vehicle expenses. An eligible taxpayer generally multiplies qualifying business mileage by the applicable IRS rate instead of separately deducting the business portion of gasoline, maintenance, repairs, insurance, registration fees and depreciation.
Taxpayers may instead use the actual expense method when eligible. Because the two methods can produce different results, preparers may want to compare them.
For an owned vehicle, a taxpayer generally must choose the standard mileage method in the first year the vehicle is available for business use to retain that option. A leased vehicle using the standard mileage method generally must continue using it for the entire lease period, including renewals.
The standard mileage method is also generally unavailable when a taxpayer operates five or more vehicles at the same time or previously claimed certain accelerated depreciation, a Section 179 deduction or special depreciation allowance on the vehicle.
Can Parking and Tolls Still Be Deducted?
Qualifying business-related parking fees and tolls may generally be deductible separately from the standard mileage amount. Preparers should distinguish deductible business parking from personal commuting expenses.
Business, Medical and Charitable Mileage in 2026
The 2026 business mileage rate is 72.5 cents per mile through June 30 and 76 cents beginning July 1. The medical and qualifying moving rate is 20.5 cents through June 30 and 23.5 cents beginning July 1.
The charitable mileage rate remains 14 cents per mile throughout 2026. Unlike the business and medical or moving rates, it did not change on July 1.
When the business standard mileage method is used, the IRS treats 35 cents per business mile as depreciation for 2026. That amount can affect adjusted basis and the gain or loss calculated when the vehicle is later disposed of.
What If a Client Did Not Separate Mileage by Date?
Preparers should not simply divide annual mileage in half or make unsupported estimates.
Ask the client to reconstruct the records using available documentation such as:
- mileage-tracking apps
- calendars
- appointment records
- invoices
- delivery records
- service logs
- expense reports
- other contemporaneous business records
Unsupported approximations should not be substituted for adequate records.
Frequently Asked Questions
What is the 2026 mileage reimbursement rate?
The business standard mileage rate is 72.5 cents per mile from January 1 through June 30, 2026, and 76 cents per mile from July 1 through December 31, 2026.
Did the IRS change the mileage rate during 2026?
Yes. The IRS increased the business rate to 76 cents per mile effective July 1, 2026.
What is the 2026 medical mileage rate?
The medical mileage rate is 20.5 cents per mile through June 30 and 23.5 cents per mile beginning July 1.
What is the 2026 charitable mileage rate?
The charitable mileage rate remains 14 cents per mile throughout 2026.
Do tax preparers need to split 2026 mileage by date?
Yes. Because different rates apply before and after July 1, qualifying mileage should be separated by date before calculating the deduction or reimbursement.
Can a taxpayer use one blended mileage rate for all of 2026?
No. The IRS published separate rates for the two periods, so the applicable rate depends on when the mileage occurred.
What Tax Preparers Should Tell Clients Now
Tax professionals should encourage clients to provide mileage records that clearly separate trips before July 1 from trips on or after July 1, 2026.
That small recordkeeping step can prevent incorrect deductions and reduce the need to reconstruct an entire year of mileage during filing season.
Keep Your Federal Tax Knowledge Current
Review the IRS Continuing Education Requirements Guide, explore the IRS/AFSP Continuing Education Package, or browse the Tax Preparer Resources hub.